株価のボラティリティというノイズに影響されず、長期的に逓増する真の価値を享受する『真のバリュー投資』に徹しています。
真のバリュー投資の定義は、次の2つに集約されます。
「真の」と付く理由は、世間一般で「割安株投資」と訳されるバリュー投資とは、明らかに異なる概念だからです。
まず①の「差異によって“儲ける”」は、真の価値と価格を常に比較する必要があります。「単に価格が安ければ、もしくは、相場が下がれば買う」という考え方では“儲けられない”ことを意味します。
「価値」とは、当該主体が自ら創造するモノ、つまり、企業が自ら創造するモノが価値であり、「価格」とは、その時々で他者が欲する分量によって決まるモノ、つまり、その時々で株主が欲する分量によって決まるモノが株価です。
世間では一般的に、「企業価値=時価総額+有利子負債」と説明され、市場の動向に影響されがちですが、株価は「価値」ではなく、単なる「(現在の)価格」です。よって、この算式に対する正しい表現は「企業時価」です。
真のバリュー投資は、企業の本質的な価値に投資しますから、株価の動向・変動やタイミングなどはノイズであり、価格自体を分析・判断の材料にすることもありません。「価値」の伴わない、単なる「株価」の値上がりを期待して儲けようとするアプローチは(たとえファンダメンタル・アプローチであっても)、基本的に投機であり、投資ではないのです。
次の②「時間を味方に付ける」は、一般的なバリュー投資のイメージのような「安く放置されている株をみつけ、上がるまで待つ」のではなく、フランチャイズバリューを創造出来るような強固な参入障壁に裏打ちされた競争優位性を持ち、それを長期的に担保して強化し続けるようなビジネスモデルが構築されている企業を「優位性が変わらない限り保有し続け、長期に連続複利で逓増する企業価値」を享受すること、つまりは、複利思考こそが真のバリュー投資の肝です。
企業が昨日稼いだキャッシュは今日へ再投資(複利運用)され、さらに今日稼いだキャッシュは明日へ再投資(複利運用)されていく、つまり「企業活動は複利計算構造を内蔵し、企業は複利的な成長を遂げるシステム」であり、複利ベースの価値創造を享受するためには、なるべく安定的にサステナブルなバリュー創出できる企業を選ぶことが肝要です。
そのためには、粘り強く徹底して投資対象と向き合い、あらゆる可能性を排除せずに仮説を立て一つ一つ検証すること、常に安全余裕率を確保した水準で投資する、つまり自律的な行動が取れること、自らの投資行動が合理的だと説明出来ること、投資の前提・想定が崩れた場合、もしくは競争優位を毀損する事実が確認出来た場合は、速やかに修正に動けること-このように冷静で謙虚なアプローチこそが求められます。
The asset management strategy of Single Family Office is firmly rooted in “True Value Investing,” which focuses on capturing true intrinsic value that grows over the long term, remains volatility-agnostic.
True value investing can be distilled into two essential principles:
We deliberately use the term “true” because this concept differs fundamentally from what is commonly referred to as “value investing,” often simplistically translated as merely investing in undervalued stocks.
The first principle — “profiting from discrepancy” — requires the continuous comparison between intrinsic value and market price. It means that one cannot generate superior returns simply by buying something because its price appears low, or because the market has declined.
“Value” refers to what an entity itself creates. In the case of a corporation, value is created through the company’s own business activities and economic output. “Price,” by contrast, is determined by the quantity desired by others at a given moment — in the equity market, by what shareholders are willing to pay at that particular time.
It is often said that “enterprise value equals market capitalization plus interest-bearing debt.” This, however, is clearly incorrect as a definition of value. It represents not value, but merely the current market price of the enterprise. Accordingly, the proper expression would be “enterprise market value,” not intrinsic value.
Because true value investing is an investment in a company’s intrinsic economic value, it does not concern itself with short-term stock price movements, market timing, or fluctuations in sentiment. Nor does it rely on price action itself as the basis for analytical judgment.
Any approach that seeks to profit merely from rising stock prices without a corresponding increase in intrinsic value — even when framed as a “fundamental” approach — is, in essence, speculation rather than investment.
The second principle — “making time your ally” — also differs materially from the conventional image of value investing as simply “finding neglected cheap stocks and waiting for them to rise.”
The essence of true value investing lies in identifying companies that possess durable competitive advantages supported by formidable barriers to entry capable of generating franchise value, together with business models that continuously reinforce and protect those advantages. Such businesses should be held for as long as their competitive superiority remains intact, thereby allowing investors to benefit from the long-term, continuously compounding growth of intrinsic corporate value.
In other words, the core of true value investing is compound thinking.
Cash generated by a company yesterday is reinvested today; cash generated today is reinvested tomorrow. Corporate activity inherently embeds a compounding structure, and superior businesses are capable of achieving compounding growth over extended periods of time. Therefore, the key to long-term value creation is selecting companies capable of generating sustainable and stable value on a recurring basis.
To identify such businesses requires persistent and rigorous engagement with each investment opportunity, forming hypotheses without prematurely excluding possibilities, and verifying them one by one with intellectual discipline. It also requires maintaining an adequate margin of safety at all times, acting with rational self-discipline, and being able to clearly explain the reasoning behind one’s investment decisions.
Equally important is the ability to respond swiftly when the original investment thesis deteriorates or when facts emerge that impair the company’s competitive advantage.
Such a calm, rational, and humble approach is indispensable to true value investing.
セミナーや勉強会、執筆活動を通じて、バリュー投資の真髄を個人投資家へ。啓蒙活動を社会貢献として運営します。
2015年にスタートした個人投資家向けプログラム『Aurea 人生と投資の会』では、主にセミナーや勉強会、或いは本やメルマガ、note等への執筆活動を通じ、バリュー投資の真髄をお伝えする機会も提供してきました。
新たにこの啓蒙活動のプラットフォーム名を『Aurea Lotus Flower』と変更し、以下の活動については、2026年以降も引き続き弊社で主宰してまいります。
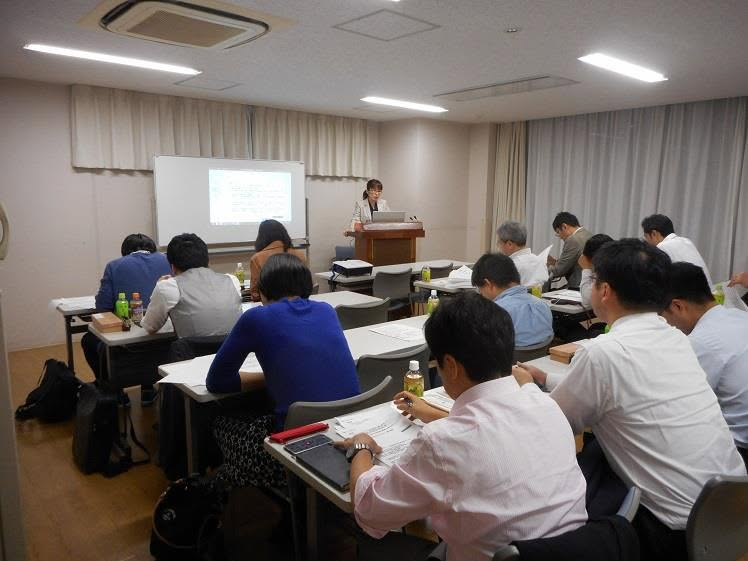
入会をご希望の方はお問い合わせフォームよりお申し付けください。
今後は、さらに多様な展開を企画しております。また、個人投資家に限らず、企業や団体等に於ける投資や経営分析に関わる勉強会・研修など、御要望がありましたら是非ご相談ください。
Since 2015, through the individual investor program “Aurea – Life & Investing Forum,” we have provided opportunities to convey the essence of value investing primarily through seminars, study sessions, and written publications.
Under the newly rebranded platform name “Aurea Lotus Flower,” the following activities will continue to be organized and hosted by our firm.
We are planning to expand our offerings in the future. In addition, we welcome inquiries from corporations, institutions, and organizations regarding seminars, workshops, and training programs related to investment analysis, corporate analysis, and business management—so please feel free to contact us if you have any requests.
 Contact
資産運用・フィランソロピー・登壇のご相談など、お気軽にお問い合わせください。
お問い合わせ →